The Power Law Lie GPs Tell Themselves
- Sahil Harwani
- September 7, 2026
- Blog
- 0 Comments
The Power Law Lie GPs Tell Themselves
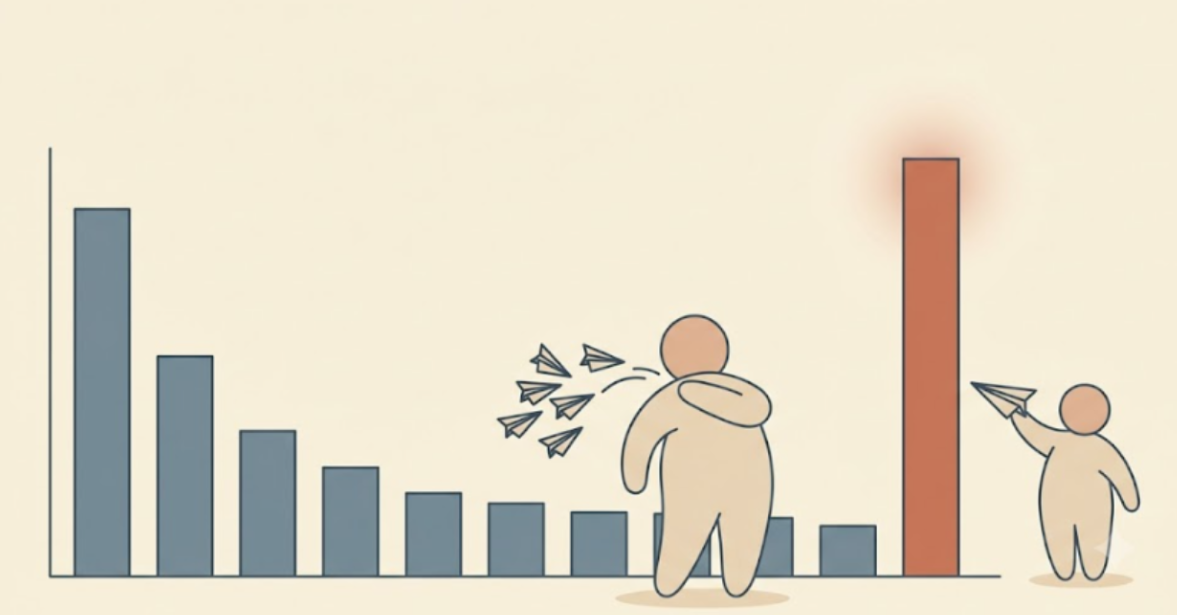
Venture returns genuinely follow a power law – a small share of deals drive most of the gains. But funds routinely misuse that fact to excuse loose screening, on the logic that “one winner covers everything, so early diligence doesn’t need to be rigorous.” The data on who actually wins under the power law says the opposite: top-quartile managers post meaningfully higher hit rates than everyone else, not lower ones. Rigor isn’t in tension with the power law. It’s the mechanism that makes it work in your favor instead of someone else’s.
A partner said it to us almost proudly, in the middle of explaining why his fund doesn’t spend much time on early-stage diligence: “It doesn’t matter – one deal will cover the whole fund anyway.” He wasn’t wrong about the math. He was wrong about what the math implies he should do about it.
The pattern behind the excuse
The textbook version of the power law is real and well documented: an analysis of roughly 7,000 venture investments over three decades found that 6% of deals generated 60% of total returns. A separate, larger study found 65% of venture deals return less than the capital invested, and only 4% return more than 10x. Say those numbers out loud in a partner meeting and the conclusion sounds obvious: most of your work will fail, so don’t over-invest in trying to prevent that.
That conclusion is where the lie sneaks in. It quietly reframes “most deals will fail” – a statement about outcomes – into “screening rigor doesn’t matter much” – a claim about process. Those are not the same statement, and the data on who actually wins under this distribution proves it.
What the data on top performers actually shows
The commonly repeated image of a great VC is someone who accepts a 90-95% loss rate in exchange for the rare outlier. The actual research on manager performance says something close to the opposite. Fund managers who consistently land in the top quartile of the industry post a “deal batting average” – the share of deals that return at least their capital back – of roughly 30-35%, and the very best managers post 40% or higher. That’s not a rounding error against the “5-10%” figure a lot of GPs assume defines a good power-law fund. It’s three to eight times higher.
Put plainly: the funds actually generating the outlier returns the power law promises are not the funds picking worse and hoping harder. They’re picking meaningfully better across the whole portfolio, and the outlier still shows up on top of that.
Why the lie is comfortable to believe
It’s comfortable because it turns a hard, ongoing discipline – rigorous, consistent early screening – into something you’re statistically excused from doing well. If one winner covers the fund regardless, why spend partner hours building a scoring framework, tracking pass patterns, or holding every deal to the same bar? The power law, misread this way, becomes permission to stop trying as hard on the 95% of deals that “don’t matter” – except the data says those are precisely the deals that separate a 35% batting average fund from a 10% one, and only one of those funds is actually a top performer.
There’s a second, quieter reason it persists: nobody audits screening rigor the way they audit returns. A fund won’t find out its diligence was loose until the vintage matures – by which point the partner who waved off the diligence discipline has usually moved on to defending the current fund instead.
What good actually looks like
The corrective isn’t “screen so hard you kill your outlier odds” – that’s the opposite failure, and it’s real too. It’s treating the power law as a reason to get better at the screening you do, not a reason to do less of it:
- Track your fund’s own deal batting average over time, the same way you track TVPI and DPI – most funds can state their headline return multiple and cannot state this number.
- Apply the same scoring discipline to every deal regardless of how excited the sponsoring partner is – conviction and rigor aren’t opposites; the best funds run both at once.
- Treat a below-30% batting average as a diagnostic worth investigating, not an accepted cost of doing business in a power-law asset class.
Where this gets hard to do consistently
The honest reason most funds don’t track their own batting average is that doing so requires every deal – not just the ones that became stories – to be scored and logged the same way, over years, regardless of who championed it or how the deal turned out. That’s a data discipline problem more than a strategy problem, and it’s exactly why so few funds can actually answer the question when an LP asks it directly.
This is the layer CompeteWiser’s gate framework exists to hold – every deal scored against the same criteria, logged the same way, whether it becomes the fund’s next headline or gets quietly written off eighteen months later. A fund that can see its own batting average clearly is a fund that’s actually testing whether its power-law bet is working, instead of just hoping it is.
Curious what your fund’s actual deal batting average looks like once it’s tracked properly? Email me at sahil@theprodzen.com.